
Unexpected expenses can create financial pressure, especially when an essential bill arrives before your next paycheck. A payday loan is one form of short-term borrowing that some people consider when they need quick access to money.
However, payday loans can be expensive, and the rules governing them vary significantly by location. Before applying, it is important to understand the total cost, repayment requirements, eligibility conditions, and possible alternatives.
This guide explains how to apply for a payday loan step by step and highlights important considerations to help borrowers make an informed decision.
What Is a Payday Loan?
A payday loan is generally a short-term loan designed to provide a relatively small amount of money that is usually repaid around the borrower’s next payday.
Depending on the lender and jurisdiction, repayment may involve a scheduled payment, electronic withdrawal, or another agreed method. Fees and interest can make the overall cost substantially higher than the amount initially borrowed.
Because payday lending laws differ by country, state, or province, borrowers should always check the rules that apply where they live.
Step 1: Decide Whether You Actually Need to Borrow
Before completing an application, consider whether borrowing is necessary.
Ask yourself whether the expense is urgent and whether there are other ways to cover it. Delaying a nonessential purchase may be preferable to taking on expensive short-term debt.
If the expense is unavoidable, compare available borrowing options rather than automatically choosing the first payday lender you find.
Step 2: Check Your Local Payday Loan Regulations
Payday lending is regulated differently in different jurisdictions.
Some locations impose limits on loan amounts, fees, repayment periods, rollovers, or lender practices. Other jurisdictions may restrict or prohibit certain forms of payday lending.
Check the relevant government or financial regulator in your area before applying. Understanding the legal framework can help you identify legitimate lenders and recognize potentially unlawful practices.
Step 3: Review Your Financial Situation
Look carefully at your income and regular expenses.
Calculate how much money you expect to have available when the loan becomes due. A loan may solve an immediate shortage but create another financial problem if the repayment leaves you unable to cover rent, utilities, food, transportation, or other necessities.
A simple budget can help determine whether repayment is realistically affordable.
Step 4: Compare Lenders and Loan Costs
Do not assume that every payday loan costs the same.
Compare the total amount you will repay, not simply the amount deposited into your account. Pay attention to fees, interest or finance charges, repayment dates, late charges, and any other costs disclosed in the agreement.
The annual percentage rate, where provided, can also help illustrate how expensive short-term borrowing can be.
A lender that advertises fast approval may not necessarily offer the lowest overall cost.
Step 5: Check the Lender’s Eligibility Requirements
Lenders typically establish their own eligibility requirements, subject to applicable laws.
Depending on the lender and jurisdiction, applicants may need to provide proof of identity, income, employment, a bank account, and contact information.
Meeting basic eligibility requirements does not necessarily mean that taking the loan is financially appropriate. Approval and affordability are separate considerations.
Step 6: Gather the Required Information
Having the necessary information ready can make the application process smoother.
A lender may request identification, proof of income, banking information, employment details, and information about existing financial obligations.
Only provide information through a legitimate lender using a secure application process. Be cautious about companies that request unnecessary sensitive information or pressure you to act immediately.
Step 7: Complete the Application
Once you have compared your options and decided that borrowing is appropriate, complete the lender’s application accurately.
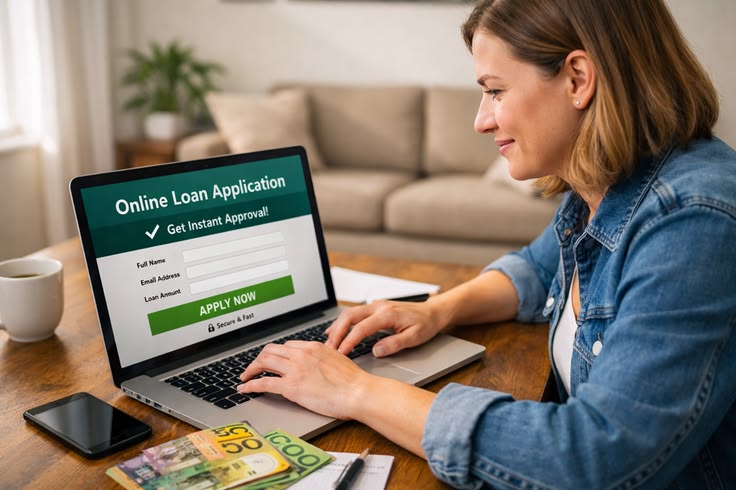
Online applications may ask you to enter personal and financial information. Some lenders also provide applications through physical locations.
Never knowingly provide false information to obtain credit. Incorrect information can cause problems during the application process and may have legal or financial consequences.
Step 8: Read the Loan Agreement Carefully
Do not accept a payday loan simply because the application was approved.
Read the agreement from beginning to end before accepting it. Look specifically for the amount borrowed, finance charges, total repayment amount, repayment date, payment method, late-payment consequences, and any additional fees.
Make sure you understand exactly how much money you will receive and how much you will have to repay.
If something is unclear, ask the lender for an explanation before agreeing to the loan.
Step 9: Confirm the Repayment Date
The repayment date is one of the most important details of a payday loan.
Short-term loans can become problematic if repayment is scheduled before you have sufficient funds available.
Mark the repayment date on your calendar and plan your budget in advance. If automatic payment is authorized, make sure you understand when the lender may withdraw funds.
Step 10: Receive the Funds
After approval and acceptance of the agreement, the lender may provide the funds through a bank deposit, cash, or another permitted method.
The timing can vary depending on the lender, banking system, and location.
Remember that receiving the money is not the end of the borrowing process. The full repayment obligation remains in place regardless of how quickly the funds were deposited.
Step 11: Repay the Loan on Time
Repaying the loan according to the agreement can help you avoid additional fees or other consequences.
Before the due date, review your account balance and make sure the necessary funds are available.
If you realize that you cannot repay the loan on time, contact the lender as early as possible. Do not assume that extending or rolling over the loan will automatically be the best solution, because additional charges can increase the total cost.
Understanding the Cost of a Payday Loan
One of the most important things to understand is that payday loans can have a high cost relative to the amount borrowed.
For example, borrowing a small amount with a fixed fee can appear affordable when viewed only as a single charge. However, the effective cost can become significant when compared with the short repayment period.
Always focus on the total amount you are required to repay.
What Happens If You Cannot Repay?
If you cannot repay a payday loan when it is due, the consequences depend on the agreement and local law.
Possible consequences may include additional fees, collection activity, account withdrawal attempts, or damage to your financial situation. Some jurisdictions establish specific protections and restrictions on collection practices.
Contacting the lender early can help you understand what options are legally available. You should also consider seeking guidance from a reputable financial counseling organization or consumer-protection agency.
Alternatives to Payday Loans
A payday loan is not the only way to deal with a temporary financial shortage.
Depending on your circumstances, alternatives may include negotiating a payment extension with a service provider, using an emergency savings fund, asking an employer about available payroll options, considering a lower-cost personal loan, or seeking assistance from a community organization.
A credit union or bank may also offer products with lower costs than payday lending in some circumstances.
The best alternative depends on your financial situation and the options available where you live.
How to Avoid Payday Loan Scams
Consumers should be particularly careful when searching for short-term loans online.
A legitimate lender should clearly disclose important terms and costs. Be cautious of websites or individuals that guarantee approval, demand unusual upfront payments, use aggressive pressure tactics, or request sensitive information through insecure channels.
Never send money to someone simply because they promise to release a loan. Verify the lender’s identity, licensing status where applicable, physical or business information, and regulatory standing before providing financial details.
Is a Payday Loan Right for You?
There is no universal answer.
A payday loan may provide quick access to funds, but its cost and short repayment period can make it difficult for some borrowers to manage. It is particularly important to consider whether repayment will interfere with essential living expenses.
If taking the loan would simply postpone a larger financial problem, another solution may be more appropriate.
Tips for Responsible Short-Term Borrowing
If you decide to use a payday loan, borrow only what you genuinely need and understand the full repayment obligation before accepting the funds.
Avoid repeatedly taking new short-term loans to cover previous loans. This can create a cycle of debt in which fees and repayment obligations continue accumulating.
Keeping a realistic budget and building an emergency fund over time can reduce the need for expensive emergency borrowing.
Frequently Asked Questions
What do I need to apply for a payday loan?
Requirements vary by lender and location. Common requirements may include identification, proof of income, contact information, and a bank account. Always check the lender’s specific requirements.
How quickly can a payday loan be approved?
Some lenders advertise rapid decisions, but approval and funding times vary. Banking processes and verification requirements can affect when funds become available.
Can I get a payday loan with bad credit?
Some payday lenders may place less emphasis on traditional credit scores than other lenders. However, eligibility requirements vary, and approval is never guaranteed.
How much does a payday loan cost?
The cost depends on the lender, amount borrowed, fees, repayment period, and applicable law. Always calculate the total repayment amount before accepting the loan.
What happens if I miss my payday loan repayment?
The consequences depend on the loan agreement and local regulations. Additional charges or collection activity may occur in some circumstances. Contact the lender promptly if you expect difficulty making the payment.
Can payday loans be renewed or extended?
Some jurisdictions and lenders may allow extensions or refinancing, while others restrict these practices. Extending a loan can increase the total cost, so carefully review the terms before agreeing.
Are payday loans available online?
Some lenders offer online applications, but borrowers should verify that an online lender is legitimate and authorized to operate in their jurisdiction where licensing applies.
What is a better alternative to a payday loan?
Potential alternatives include a lower-cost personal loan, credit-union financing, negotiating payment arrangements, emergency savings, employer-based options, or assistance from community organizations. The best choice depends on your circumstances.
Conclusion
Applying for a payday loan can be a relatively straightforward process, but deciding whether to take one requires much more consideration. Before applying, assess your budget, research applicable regulations, compare lenders, understand the total cost, and carefully review the repayment terms.
Most importantly, do not focus only on how quickly you can receive the money. Consider how the repayment will affect your finances after the immediate emergency has passed.
If you decide that a payday loan is necessary, borrow cautiously, understand the agreement, and have a realistic plan for repayment. When possible, compare lower-cost alternatives and work toward building an emergency fund that can reduce the need for high-cost short-term borrowing in the future.